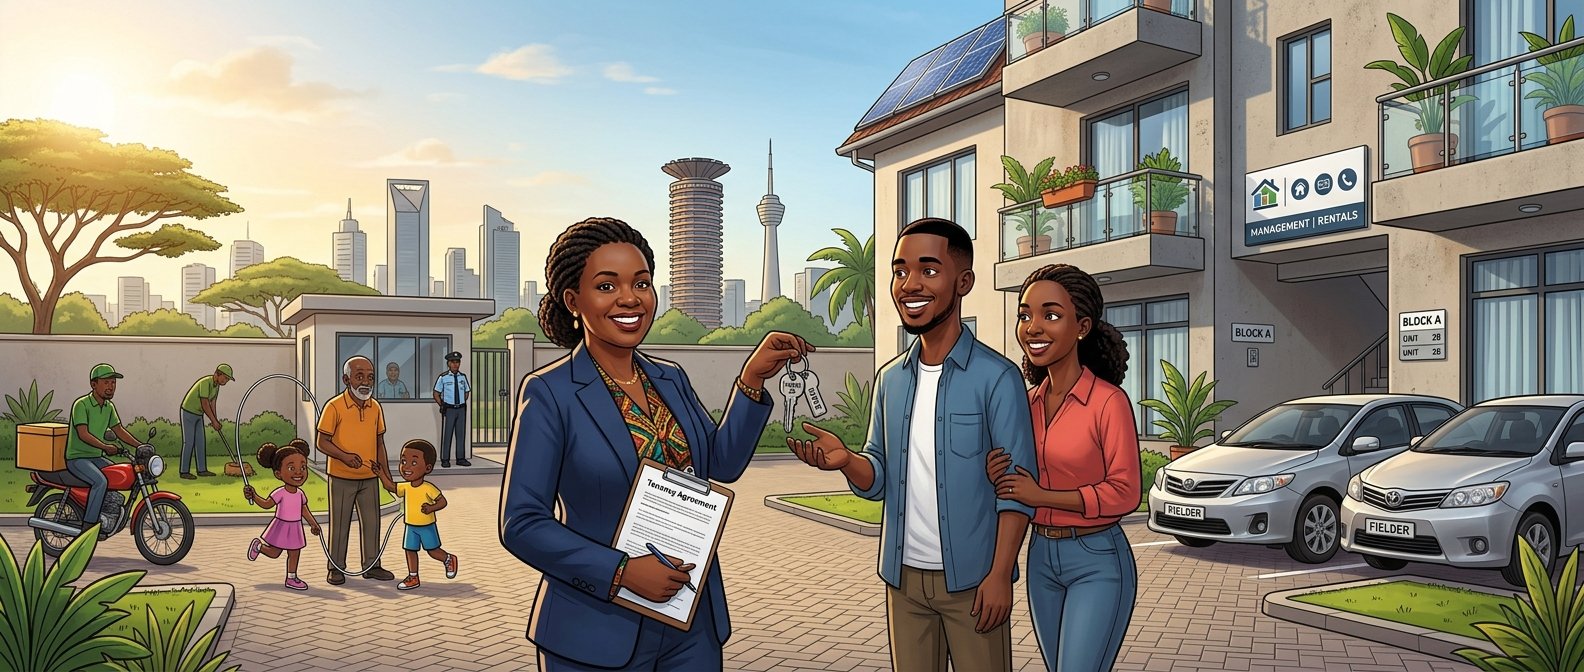
Collecting rent is rarely as effortless as real estate ads suggest. In Kenya’s rental market, your actual yield depends entirely on how effectively you manage everyday operations.
If you want a reliable income stream that survives market shifts, you need a proactive strategy that protects your money and your peace of mind.
1. Run your rental like a business
Treating rental income as personal pocket money creates accounting blind spots that quickly hide your true net yield. Instead of mixing accounts, you should treat your property as a distinct business entity from day one.
Set up a dedicated bank account or M-Pesa Till number exclusively for your property. Ensure every rent payment enters this account, while every repair, land rate, and apartment service charge comes directly out of it.
Furthermore, keeping clear digital records removes guesswork during tax season and establishes clear professional boundaries with your tenants.
2. Tighten your tenant vetting
A vacant unit costs money, but placing the wrong tenant costs far more. Since formal credit scores are rare in Kenya, you must verify financial behavior directly before handing over the keys.
Ask prospective tenants for their last three to six months of bank or M-Pesa statements so you can confirm income consistency before signing anything.
Next, verify their employment details and call their previous landlord. A quick conversation reveals whether they pay on time, respect estate rules, or leave a trail of unpaid bills behind.
3. Write a clear, enforceable lease
Verbal agreements and generic online templates leave you completely exposed when disputes arise. Therefore, you need a strong lease agreement that sets clear ground rules under Kenyan law.
Specify the exact rent due date, accepted payment channels, grace periods, and late fees. Clearly state who pays for garbage collection, security, and water tokens.
Most importantly, outline the exact conditions for returning security deposits, ensuring that exiting tenants clear all utility bills before you refund their money.
4. Price for neighborhood realities
Pricing your unit too high out of emotion is a costly mistake. For instance, if an apartment sits empty for two months because you asked for KSh 3,000 above market value, you lose money you will never recover.
Survey surrounding estates to understand real local supply and current absorption rates. Look at what similar units actually rent for, rather than relying on what landlords ask on listing platforms.
By pricing slightly below peak market rates, you attract a larger pool of qualified applicants, which lets you pick the best tenant and enjoy low turnover.
5. Stay ahead of property repairs
Ignoring a minor roof leak or a slow plumbing trickle today guarantees a massive bill tomorrow. After all, deferred maintenance degrades your asset and gives good tenants a reason to move out.
Schedule regular physical inspections, especially right after heavy rainy seasons. Inspect water storage tanks, borehole pumping systems, drainage channels, and external paintwork.
Fixing minor defects early keeps your maintenance budget predictable. Meanwhile, it shows tenants that you take genuine pride in maintaining the building.
6. Retain your best tenants
Tenant turnover is a major profit killer. Every time someone moves out, you lose money on repainting, advertising, repairs, and empty months.
Keeping reliable tenants comes down to responsiveness and respect. When a tenant reports a broken pipe or a security issue, resolve it promptly.
Additionally, communicate transparently about estate maintenance or planned utility disruptions. Tenants who feel valued stay longer, giving you predictable cash flow year after year.
7. Enforce rent policies fairly
Even good tenants run into financial difficulties, but lax enforcement creates bad habits. If you let payment deadlines slide without communication, late payments quickly become the norm.
Establish firm deadlines and follow up immediately when a payment is missed. However, if a tenant faces a genuine setback, put a short-term payment plan in writing instead of letting debt pile up unchecked.
If non-payment continues and the tenant refuses to cooperate, move swiftly using legal distress-for-rent protocols through licensed auctioneers to cut your losses.
8. Plan for hidden statutory expenses
Gross rental income is never your net profit. First-time landlords are often shocked by recurring statutory costs that steadily eat into their returns.
You must account for KRA Residential Rental Income Tax (RRIT), which the tax authority calculates on gross rent collected. In addition, factor in annual land rates, county government fees, estate service charges, and potential tenant utility arrears.
Set aside 10% to 15% of your monthly rental income into a reserve fund so these expenses never catch you off guard.
9. Know when to hire an agent
Managing a property yourself saves money, but it costs significant time and energy. As your portfolio grows or if your rentals sit far from where you live, direct management gets exhausting.
Evaluate whether paying a 5% to 10% management fee to a reputable property agent makes sense for your schedule.
A competent agent handles tenant sourcing, rent collection, emergency maintenance, and daily friction on the ground. Delegating these tasks lets you focus on finding your next investment instead of chasing late rent.
Bottom Line
Successful landlording in Kenya requires actively managing risk, protecting your physical asset, maintaining legal boundaries, and building respectful relationships. When you treat your rentals like a professional business, you protect your yield and build lasting wealth.


Join The Discussion